

Deferit: Split Bills, Pay in 4

- 2.30K Reviews
- 4.6
- Downloads
- 1,000,000+
Our take on Deferit: Split Bills, Pay in 4 from Appgk
When a bill arrives at the wrong time, the problem is often not the total amount but the timing. That is the situation I found most interesting about Deferit: Split Bills, Pay in 4. Developed by Deferit, this free finance app is built around one clear idea: divide an eligible bill into four smaller payments instead of handling the whole amount at once. In my experience, that makes it more useful as a short-term budgeting tool than as a general money-management app.
The appeal is easy to understand. A large utility, phone, insurance, or household bill can collide with rent, groceries, or an unexpected expense. Spreading the payment can make the month feel more manageable, particularly for someone whose income and bills do not line up neatly. The important point is that this is not extra income. It is a way to change the timing of an expense, and that distinction should guide how you use it.
Deferit has become a well-known option in its niche, with an average rating of 4.6 from around 20 thousand ratings and more than a million installs. It is rated for Everyone, runs on Android 7.0 or later, and the current version is 3.0.6. Those details make it accessible to a broad range of users, although the real question is whether splitting a bill fits your personal cash flow without creating another problem later.
Splitting one large bill into four manageable steps
The central capability is deliberately narrow. Instead of paying a bill in one transaction, the app lets you arrange four smaller payments with no interest. That can be a meaningful difference when the full charge would empty an account, but each smaller amount is realistic. The benefit comes from reducing the size of the immediate payment, not from making the bill cheaper.
Best Parts of Deferit: Split Bills, Pay in 4
Things to Keep in Mind About Deferit: Split Bills, Pay in 4
I think this framing matters because “pay later” products can sound more flexible than they really are. Deferit is most sensible when you already know how the next few weeks of your budget will look. If the four scheduled payments fit comfortably, the arrangement can smooth out a difficult week. If they do not, the app may only postpone the pressure and make your following weeks tighter.
The strongest use case is a predictable bill with a known amount. A recurring household expense is easier to plan around than an uncertain purchase or an impulse expense. Before using the service, I would look at the complete month ahead, mark the dates when money comes in, and check whether all four portions can be covered alongside essentials. That simple check is more important than the convenience of starting the split quickly.
News and Features Related to Deferit: Split Bills, Pay in 4

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
There is also a psychological advantage. A single large bill can dominate a weekly budget, while four smaller amounts are easier to place beside ordinary spending. That does not change the underlying obligation, but it can make a planned budget easier to follow. For someone who tends to react to bills one at a time, this structure may provide a clearer rhythm.
What the experience is like in everyday use
In practical terms, I would approach Deferit as a short sequence rather than a one-tap escape from a bill. First, I would identify the bill that needs attention and make sure it is the kind of expense I can responsibly spread. Then I would review the payment arrangement carefully, paying attention to the amount and timing of each portion before committing.
Don't want to read the full review?
That review step is where many users will decide whether the app helps or hurts. A smaller first payment can look attractive, but the remaining portions still have to be treated as fixed commitments. I would record them in the same calendar or budgeting system I use for rent and subscriptions. Relying only on memory is risky, especially when several bills are already being paid automatically.
The app’s value is therefore connected to organization. It can make a large payment easier to absorb, but it cannot replace checking balances, planning paydays, or leaving room for emergencies. I would not use it as permission to spend money that is already allocated elsewhere. I would use it only after deciding that the divided schedule is genuinely affordable.
Screenshots
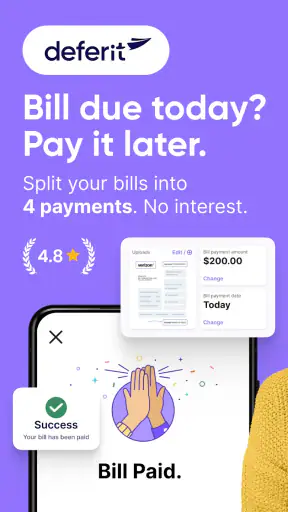
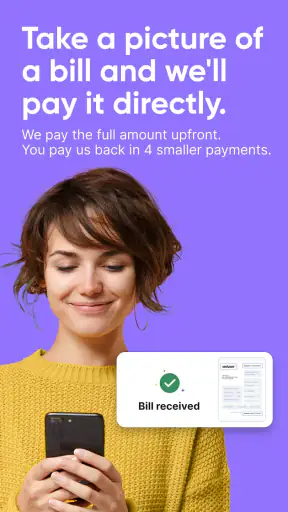
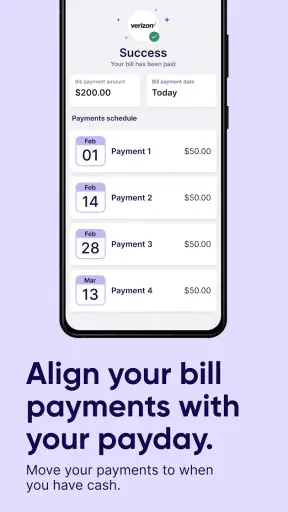
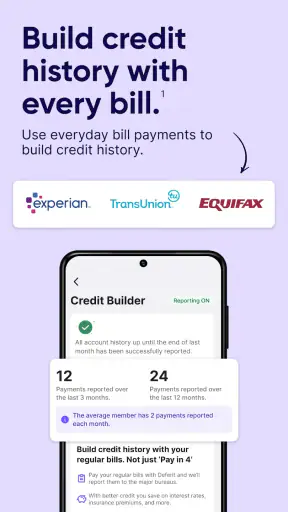
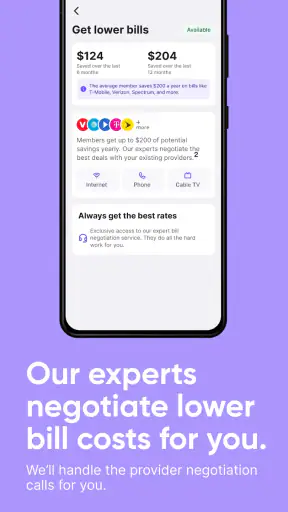
One useful habit is to reserve the later portions as soon as the arrangement is created. If I received income before the first payment, I would mentally separate the money needed for the remaining payments instead of treating the balance as available spending cash. This is a small but important distinction: the app changes payment timing, while a personal budget protects the money required to complete the arrangement.
Another practical consideration is bill concentration. Splitting one bill may solve a problem, but splitting several bills at once can create a crowded schedule of smaller withdrawals. I would start with one predictable expense and observe how it fits into the month before relying on the same approach for multiple obligations. The convenience grows quickly, but so can the number of dates to track.
A realistic month where the feature makes sense
Imagine a household facing a larger-than-usual utility bill just after paying rent. The bill is necessary, the amount is known, and the person expects income again before the month ends. Paying the entire charge immediately would leave too little for groceries and transport, while four smaller payments could fit more naturally across the month.
In that situation, Deferit could provide breathing room without interest. I would still write down every scheduled portion, reduce optional spending temporarily, and keep a small buffer for an unexpected cost. The app would be doing its best work here: helping with timing on a necessary expense that the user expects to cover, rather than financing something optional.
The same arrangement becomes less comfortable if that person already has several payment commitments. A bill that looks manageable in isolation may become difficult when combined with other deferred expenses. I would therefore judge the app by the whole cash-flow picture, not by whether the first portion feels affordable.
This is also why the service may appeal to people paid weekly, irregularly, or on dates that do not match their billing cycle. Smaller scheduled amounts can be easier to align with incoming money. However, irregular income requires extra caution. A projected payday is not the same as money already available, and a delayed paycheck can affect every later portion of the plan.
Where it compares well with ordinary alternatives
The usual alternative is to pay the bill in full from a bank account. That is simpler and avoids creating a series of future obligations, so it remains the better choice whenever the full amount can be paid comfortably. Full payment also requires less tracking and leaves no split schedule to manage.
Another alternative is a credit card. A card may offer flexibility, but the eventual cost can depend on how the balance is handled. Deferit’s no-interest split structure is easier to understand for someone who wants four defined payments rather than a revolving balance. On the other hand, a credit card may be more suitable for a person who needs broader spending flexibility and already manages repayments carefully.
Borrowing from family or friends can avoid formal payment arrangements, but it can also create personal pressure. Deferit offers a more structured route for the specific purpose of dividing a bill. That structure is useful when the user wants clear scheduled payments, though it does not remove the responsibility to complete them.
A traditional emergency fund is still the healthiest long-term answer. Savings can cover a bill without creating future deductions, while Deferit is mainly a timing solution. I see the app as a bridge for a short-term mismatch, not a substitute for building a reserve. If every month requires a split payment, the deeper issue may be that regular expenses are too close to regular income.
The trade-offs I would consider before starting
The first trade-off is simplicity versus flexibility. Paying in full is straightforward. Dividing a bill creates more dates, more reminders, and more opportunities to lose track. The smaller amount may feel easier, but the arrangement demands better organization.
The second is short-term relief versus future room. A split payment can free up money today, but each later portion takes space from a future budget. I would be especially careful before using it near a month that already includes annual renewals, school expenses, travel, or other known costs.
The third is confidence versus uncertainty. The app is a better fit when the bill is predictable and the user’s income is dependable. It is a weaker fit when income is volatile, expenses change suddenly, or the user is already using several forms of borrowed flexibility. In those cases, adding another schedule can make the financial picture harder to understand.
I also would not choose it for a purchase that I could simply postpone. A necessary bill may justify solving a timing problem; a nonessential purchase usually does not. If waiting a few days or weeks removes the need to split the payment, waiting is the cleaner financial decision.
Users should also take the arrangement seriously because “no interest” does not mean “no responsibility.” The absence of interest is attractive, but it does not make missed planning harmless. I would read the in-app payment details carefully, keep notifications enabled if available, and maintain a separate reminder outside the app. A second reminder is worthwhile for any payment schedule that affects essentials.
Small workflow improvements that make it safer
My preferred workflow would begin with a bill inventory. I would list the amount, the original due date, the dates of expected income, and the other fixed payments already planned. Only after that would I decide whether splitting the bill improves the month or merely shifts the problem.
I would then create a dedicated note for the arrangement, including the four portions and the dates shown in the app. This is more reliable than remembering that a bill was “mostly handled.” The important information is not just the first payment but the entire sequence.
A further improvement is to use the app selectively. I would choose the bill whose timing causes the most strain while leaving smaller, easily affordable bills alone. Splitting everything can make a budget look comfortable at first but complicated later. One carefully chosen arrangement is easier to monitor than several overlapping ones.
Finally, I would review the result after the schedule ends. Did the split genuinely prevent a difficult week, or did it make the next month more restricted? That answer tells me whether the tool is solving a temporary mismatch or masking a recurring shortfall. This kind of review is more useful than judging the app only by how convenient the initial setup felt.
Who is likely to benefit most
Deferit is best suited to someone who has a necessary bill, expects to pay it in full, and needs a little more space between today’s expense and later income. It can be particularly practical for people whose billing dates regularly arrive before their pay cycle, provided the four portions remain comfortable.
It may also help a careful budgeter who wants a defined alternative to carrying a credit-card balance. The fixed four-part structure is easier to reason about than an open-ended balance, and the no-interest design can be appealing when the user is disciplined about completing the schedule.
I would advise more caution for anyone already behind on bills, frequently overdrawing an account, or using one payment arrangement to cover another. In that situation, the app may make individual payments appear smaller while the overall obligations continue growing. A conversation with a financial counselor or a review of essential spending would be more useful than adding another short-term solution.
People who dislike reminders and scheduled deductions may also prefer paying directly. The app’s strength depends on accepting a little extra structure. If tracking four portions feels stressful, the convenience may not outweigh the mental load.
As a finance app, Deferit is focused rather than comprehensive. I would not install it expecting a full banking replacement, a complete spending dashboard, or a long-term savings system. Its purpose is much more specific: helping divide a bill into four interest-free payments. That narrow focus is a strength when your problem matches it and a limitation when you need broader financial planning.
My final view after weighing the feature
I like the idea behind Deferit because it addresses a common, concrete problem without pretending that a bill has disappeared. The four-payment approach can turn an uncomfortable payment date into a more manageable schedule, and the no-interest structure is easier to understand than carrying an uncertain balance.
My recommendation comes with a firm condition: use it only when the complete schedule fits your budget. I would choose it for a predictable essential bill during a temporary timing squeeze, not for recurring overspending or optional purchases. I would also keep an independent record of every portion and avoid stacking several arrangements without a clear monthly plan.
With that discipline, this free app from Deferit can be a useful pressure-release tool. Its 2021 release and current 3.0.6 version show an established product rather than a brand-new experiment, while its broad adoption suggests that the basic concept resonates with many users. Still, popularity does not replace personal affordability.
My honest takeaway is that Deferit works best when it changes timing, not when it hides a shortage. If you have the money coming and need to spread the impact of one bill, it is worth considering. If you are unsure how the later payments will fit, paying directly, postponing a nonessential expense, or strengthening your budget would be the safer choice.
Deferit: Split Bills, Pay in 4 FAQ
What is Deferit: Split Bills, Pay in 4?
Deferit is a financial app designed to help eligible users manage certain bills and everyday expenses. Depending on availability in your region, it may allow you to pay a bill through the app and repay the amount later, sometimes using scheduled installments. It can be useful for short-term budgeting, but users should carefully review the repayment terms, eligibility rules, and total cost before signing up.
How does Deferit’s bill-splitting or Pay in 4 feature work?
After creating an account and completing any required verification, eligible users may submit supported bills or purchases through Deferit. The app then explains the available payment schedule, which may divide the amount into several installments. Approval is not guaranteed, and the exact options can depend on your location, account history, bill type, and other eligibility checks. Always confirm the schedule before accepting.
Does Deferit charge fees or interest?
Deferit’s costs can vary according to the service you use, your location, and the terms shown in the app. Some features may involve membership, transaction, processing, late, or other applicable fees, while certain plans may not charge traditional interest. Before proceeding, read the complete pricing information and repayment agreement carefully. Missing a payment could also result in additional charges or account restrictions.
Is Deferit safe to use with my personal and financial information?
Deferit may request personal, identity, banking, income, or bill information in order to verify your account and assess eligibility. The app should be downloaded only from an official app store, and users should review its privacy policy, permissions, and security information before registering. Use a strong, unique password, avoid sharing verification codes, and contact official support if you notice suspicious activity.
What should I know before downloading and using Deferit?
Before downloading Deferit, check whether the service is available in your country and whether your preferred billers, payment methods, and device are supported. You may need to meet age, identity, residency, or financial eligibility requirements. Remember that installment services are still a financial commitment: create a realistic repayment plan, monitor due dates, and avoid using the app to borrow more than you can comfortably repay.











